Medical debt and bankruptcy in Texas: can bankruptcy wipe out hospital bills?
 It only takes one medical emergency to push most families into a financial spiral. If you’re struggling with medical debt and wondering if bankruptcy will help… Yes, it will! Medical debt is unsecured debt, and unsecured debt is dischargeable in bankruptcy. A patient who qualifies for Chapter 7 can eliminate hospital bills, emergency room balances, surgical charges, and specialist fees in full. A patient who files for Chapter 13 repays a portion of medical debt through a court-approved plan and discharges the remaining balance at the end of the plan. Medical bills are among the most common debts listed in Texas bankruptcy cases, and no rule requires a filer to prove that a medical emergency caused the debt.
This page explains how bankruptcy treats medical debt in Texas, what a filing stops, and which mistakes can make a difficult situation worse. (more…)
 If you are facing a pending bankruptcy and divorce at the same time, you are probably wondering which case should be filed first in Texas. There is no correct order for everyone. For many couples, the better sequence is to file for bankruptcy first, together, and complete the divorce afterward. A joint bankruptcy case can eliminate the debts of the marriage before a divorce court divides what remains, and it does so for one filing fee. For other couples, particularly when one spouse earns substantially more than the other or when the divorce itself is contested, completing the divorce first yields a better financial outcome. The right order depends on whose names appear on the debts, how much each spouse earns, what property the couple owns, and whether the spouses can cooperate long enough to complete a joint filing.
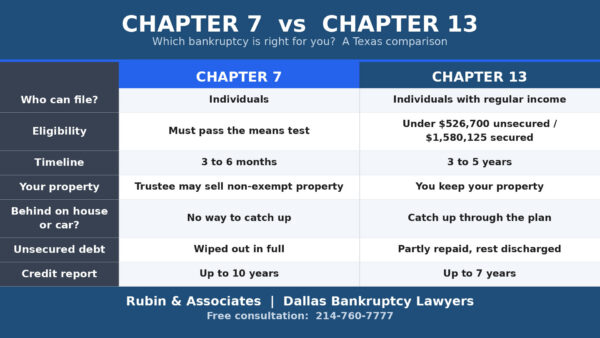 Most people who consider bankruptcy in Texas face the same first question: should I file Chapter 7 or Chapter 13? The two chapters work very differently, and it is important to understand the differences. Chapter 7 eliminates qualifying debt in a matter of months. Chapter 13 restructures debt into a court-supervised repayment plan that lasts three to five years. Neither is better in the abstract. The right choice depends on your income, your assets, whether you are behind on secured debts like a mortgage or car loan, and what you need the bankruptcy to accomplish. This guide compares the two chapters side by side so you can understand which path fits your situation.
 The short answer: what Chapter 7 costs in Dallas